Blog

  • Japan Daily Update — 16 August 2026

    Japan News Digest — Sunday, August 16, 2026
    Your weekly roundup of what’s happening in Japan, from food trends to geopolitics. Here’s what you need to know this week.

    Chilled Noodles: Japan’s Answer to Brutal Summer Heat

    As Japan enters its peak summer season, cold sōmen noodles are becoming essential for expats navigating the sweltering temperatures. This traditional Japanese dish offers a practical, delicious way to stay cool while enjoying authentic local cuisine—perfect for your meal planning during humid months.

    Read full story

    Tokyo’s Chicken Rice Boom: Singapore’s Premium Restaurant Opens in Japan

    Tokyo’s dining scene is rapidly diversifying, with Singapore’s top-rated chicken rice restaurant now joining the capital’s expanding international food landscape. If you’re craving authentic Asian cuisine beyond traditional Japanese fare, this expansion signals more diverse dining options arriving in major cities.

    Read full story

    Japanese Horror and Mystery Literature Gains Global Audience

    Japanese crime, mystery, and horror fiction is experiencing a surge in English-language readership, making it easier for expats to explore Japan’s literary culture. This trend reflects growing international interest in Japanese storytelling and provides accessible entry points into the country’s unique creative traditions.

    Read full story

    South Korea Signals Deeper Partnership with Japan

    South Korea’s president has publicly called for expanded cooperation with Japan, signaling potential improvements in bilateral relations. For expats in either country, closer ties between these neighboring nations could facilitate easier cross-border travel, business opportunities, and cultural exchange.

    Read full story

    Robots Offer Lifeline to Japan’s Aging Rural Communities

    As Japan’s farming regions face severe demographic challenges, innovative robot technology is stepping in to handle dangerous and labor-intensive tasks. This trend highlights Japan’s broader efforts to maintain rural livelihoods through automation—something expats in rural areas may increasingly encounter.

    Read full story

    Japan Weighs Response to Putin’s Disputed Island Visit

    Japan is considering its diplomatic and economic response to Russia’s recent actions, with options ranging from enhanced sanctions to temporary recall of its ambassador. Expats should monitor geopolitical developments in the region, as they can affect bilateral relations and broader regional stability.

    Read full story

    Check back tomorrow for the latest Japan updates.


    Compiled daily from Japan Times and GaijinPot. Updated every morning.

  • Private Health Insurance vs NHI in Japan for Expats: Which One Do You Actually Need in 2026?

    Private Health Insurance vs NHI in Japan for Expats: Which One Do You Actually Need in 2026?

    Affiliate Disclosure: This article contains affiliate links. If you click through and make a purchase or sign up for a service, I may earn a small commission at no extra cost to you. I only recommend products and services I’ve personally used or thoroughly researched. Your support helps keep this site running — thank you!

    Introduction: The Health Insurance Question Every Expat Faces

    Here’s something that catches a lot of new arrivals off guard: Japan doesn’t just offer health insurance — it requires it. Every resident, including expats, must be enrolled in some form of health insurance. No exceptions. No “I’ll just wing it and pay cash” option. Well, technically you can try that, but you’ll be breaking the law and potentially facing backdated premiums that’ll make your eyes water.

    So the real question isn’t whether you need health insurance in Japan — it’s whether the mandatory National Health Insurance (NHI) system is enough, or whether you should layer on private health insurance too. And honestly? The answer depends on your specific situation more than most blog posts will admit.

    I’ve been through this decision multiple times over the years — as a language school student, as an employee at a Japanese company, as a freelancer, and now as someone helping others navigate the same maze. Let me break down what I’ve learned so you can make a genuinely informed choice in 2026.

    Before we dive in, if you’re still in the planning stages of your move, check out our comprehensive moving to Japan checklist to make sure you’ve got all your bases covered.

    Understanding Japan’s National Health Insurance (NHI) System

    First, let’s get the terminology straight. Japan has two main public health insurance systems:

    • Shakai Hoken (社会保険) — Employee Health Insurance, which you’re automatically enrolled in if you work for a company with five or more employees. Your employer pays roughly half, and your portion is deducted from your paycheck.
    • Kokumin Kenko Hoken (国民健康保険) — National Health Insurance (NHI), which covers everyone else: freelancers, self-employed people, students, retirees, and those between jobs.

    Both systems work similarly from a coverage perspective. You pay a percentage of your income as premiums, and in return, the system covers 70% of your medical costs. You pay the remaining 30% out of pocket at the point of care.

    What NHI/Shakai Hoken Actually Covers

    The coverage is genuinely impressive for a public system:

    • Doctor visits and specialist consultations
    • Hospitalization (including meals during your stay)
    • Surgery
    • Prescription medications
    • Mental health treatment
    • Maternity care (though not normal delivery — that’s considered non-medical)
    • Dental care (basic treatments)
    • Rehabilitation
    • The High-Cost Medical Expense Benefit (Kogaku Ryoyo-hi), which caps your monthly out-of-pocket spending based on your income

    That last point is crucial and often overlooked. If you need major surgery or extended hospitalization, the High-Cost Medical Expense Benefit kicks in and limits what you actually pay. For an average income earner in 2026, that cap is roughly ¥80,000-¥90,000 per month. This means even a ¥2,000,000 surgery would only cost you around ¥80,000 out of pocket.

    What NHI Doesn’t Cover

    • Private hospital rooms (you’ll share a room with others)
    • Advanced medical treatments not yet approved in Japan
    • Most dental cosmetic work and orthodontics
    • Certain cutting-edge cancer treatments
    • Medical care received outside Japan
    • Vision correction surgery (LASIK)
    • Some preventive screenings (though many are subsidized by your ward office)
    • Normal childbirth (though a lump-sum grant of ¥500,000 is provided)

    NHI Cost Breakdown for Expats in 2026

    NHI premiums vary by municipality and are calculated based on your previous year’s income. Here’s a rough guide:

    • First year in Japan (no prior Japanese income): Often quite low — around ¥2,000-¥5,000/month in many cities
    • Annual income of ¥3,000,000: Roughly ¥15,000-¥25,000/month
    • Annual income of ¥5,000,000: Roughly ¥25,000-¥40,000/month
    • Annual income of ¥8,000,000+: Can reach ¥50,000-¥65,000/month
    • Maximum cap: Around ¥1,060,000/year in 2026 (varies by municipality)

    For Shakai Hoken, expect roughly 5% of your gross salary, with your employer matching that amount.

    Private Health Insurance Options for Expats in Japan

    Private health insurance in Japan falls into two main categories: Japanese domestic private insurance and international private health insurance. They serve very different purposes.

    Japanese Domestic Private Insurance (Minkan Hoken)

    These plans are designed to supplement your NHI coverage, not replace it. Think of them as gap-fillers. The most common types include:

    • Medical insurance (iryo hoken): Pays a daily hospitalization benefit (e.g., ¥5,000-¥10,000 per day) and lump sums for surgery
    • Cancer insurance (gan hoken): Specific coverage for cancer diagnosis and treatment
    • Life insurance with medical riders: Combines life coverage with health benefits
    • Income protection insurance: Replaces income if you’re unable to work due to illness or injury

    Major providers include Aflac Japan, Sony Life, MetLife Japan, Zurich Japan, and various Japanese companies like Nippon Life and Dai-ichi Life.

    International Private Health Insurance

    These are comprehensive plans from global insurers, designed for expats and globally mobile professionals. They typically offer:

    • Worldwide coverage (including trips home)
    • Choice of hospitals globally, including private facilities
    • English-language customer service
    • Direct billing at partner hospitals
    • Evacuation and repatriation coverage
    • Higher coverage limits
    • Optional dental and vision plans

    Key providers include Cigna Global, Allianz Care, AXA International, BUPA Global, and IMG (International Medical Group).

    Cigna Global Health Insurance: Best Overall for Expats

    Cigna Global consistently ranks as one of the top choices for expats in Japan, and having dealt with them both personally and through other expats’ experiences, I understand why.

    Their Silver plan starts around $2,500-$4,000/year depending on your age, and offers up to $1,000,000 in annual coverage. The Gold and Platinum plans go higher, with Platinum offering unlimited inpatient coverage.

    Pros:

    • Excellent English-language support available 24/7
    • Large network of partner hospitals in Japan
    • Flexible plan customization — add outpatient, dental, vision, or maternity as needed
    • Covers you globally, not just in Japan
    • Direct billing at many hospitals eliminates reimbursement hassle
    • User-friendly online portal and mobile app for claims

    Cons:

    • Premiums increase significantly with age (especially past 40)
    • Pre-existing conditions are typically excluded or subject to waiting periods
    • Doesn’t exempt you from NHI enrollment — you’ll still need to pay NHI premiums in most cases
    • Can be overkill if you’re healthy and only staying a few years

    Allianz Care: Best for Families

    Allianz Care’s international plans are particularly well-suited for expat families in Japan. Their family plans offer genuine value compared to insuring each member separately.

    Pros:

    • Comprehensive maternity coverage (after waiting period)
    • Excellent pediatric coverage
    • Wellness benefits including vaccinations and health screenings
    • Strong presence in Asia with good hospital networks
    • Mental health coverage included in most plans

    Cons:

    • Premiums for family plans can exceed $10,000/year
    • Claims process can be slower than Cigna in some cases
    • Some Japan-specific treatments may require pre-authorization

    Aflac Japan: Best Domestic Supplemental Insurance

    If you’re already enrolled in NHI and just want to fill the gaps, Aflac Japan is the most expat-friendly domestic option. They’re huge in Japan — you’ll see their duck mascot everywhere — and they’ve been offering plans to foreign residents for years.

    Pros:

    • Affordable premiums — basic medical plans start around ¥2,000-¥4,000/month
    • Cancer insurance is their specialty and genuinely excellent
    • Some English-language support available
    • Premiums are tax-deductible in Japan (up to certain limits)
    • No-claims bonuses on some plans

    Cons:

    • Limited English documentation — most materials are in Japanese
    • Doesn’t cover you outside Japan
    • Sign-up process is usually in Japanese
    • Benefit amounts are fixed rather than percentage-based

    If you need help navigating Japanese-language insurance documents, having a solid language learning app on your phone can be surprisingly useful for reading through basic terms and conditions.

    SafetyWing Nomad Insurance: Best Budget Option for Remote Workers

    If you’re in Japan on a working holiday visa, digital nomad visa, or just starting out and need affordable coverage while you get NHI sorted, SafetyWing is worth considering.

    Pros:

    • Extremely affordable — around $45-$85/month depending on age
    • Easy online signup — takes about 5 minutes
    • Includes some coverage in your home country (up to 30 days per 90-day period)
    • Good for short-to-medium term stays
    • No commitment — cancel anytime

    Cons:

    • Lower coverage limits than comprehensive plans ($250,000 maximum)
    • Not a substitute for NHI if you’re a registered resident
    • Limited dental coverage
    • Deductible of $250 per condition
    • Not ideal for long-term residents or those with ongoing health needs

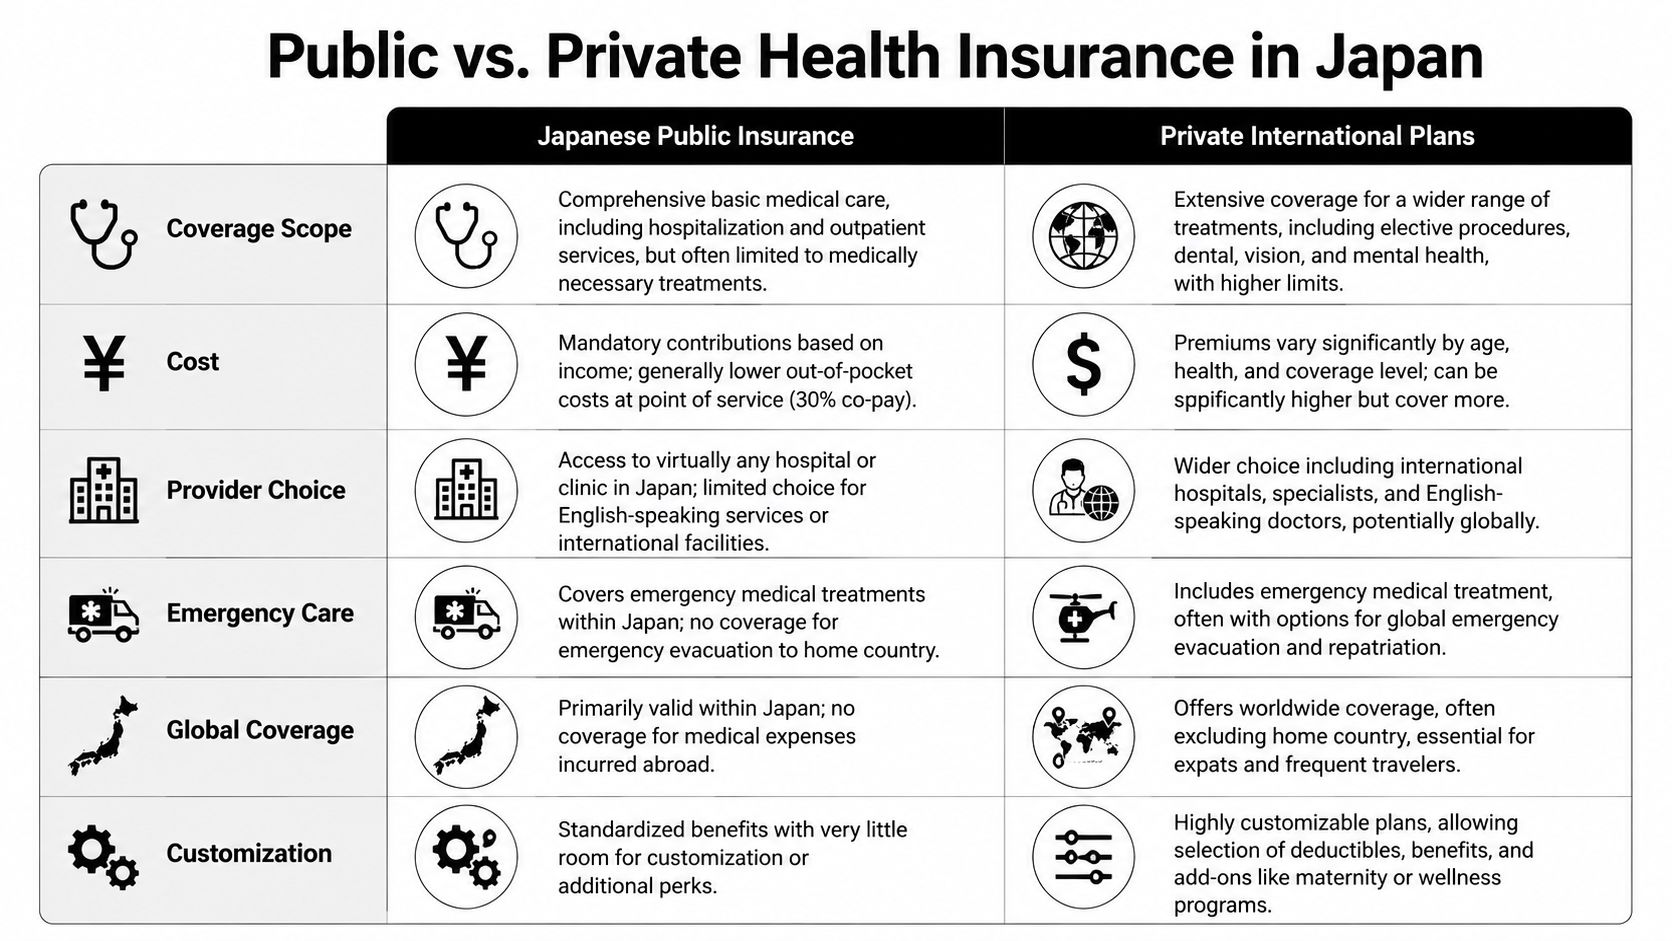
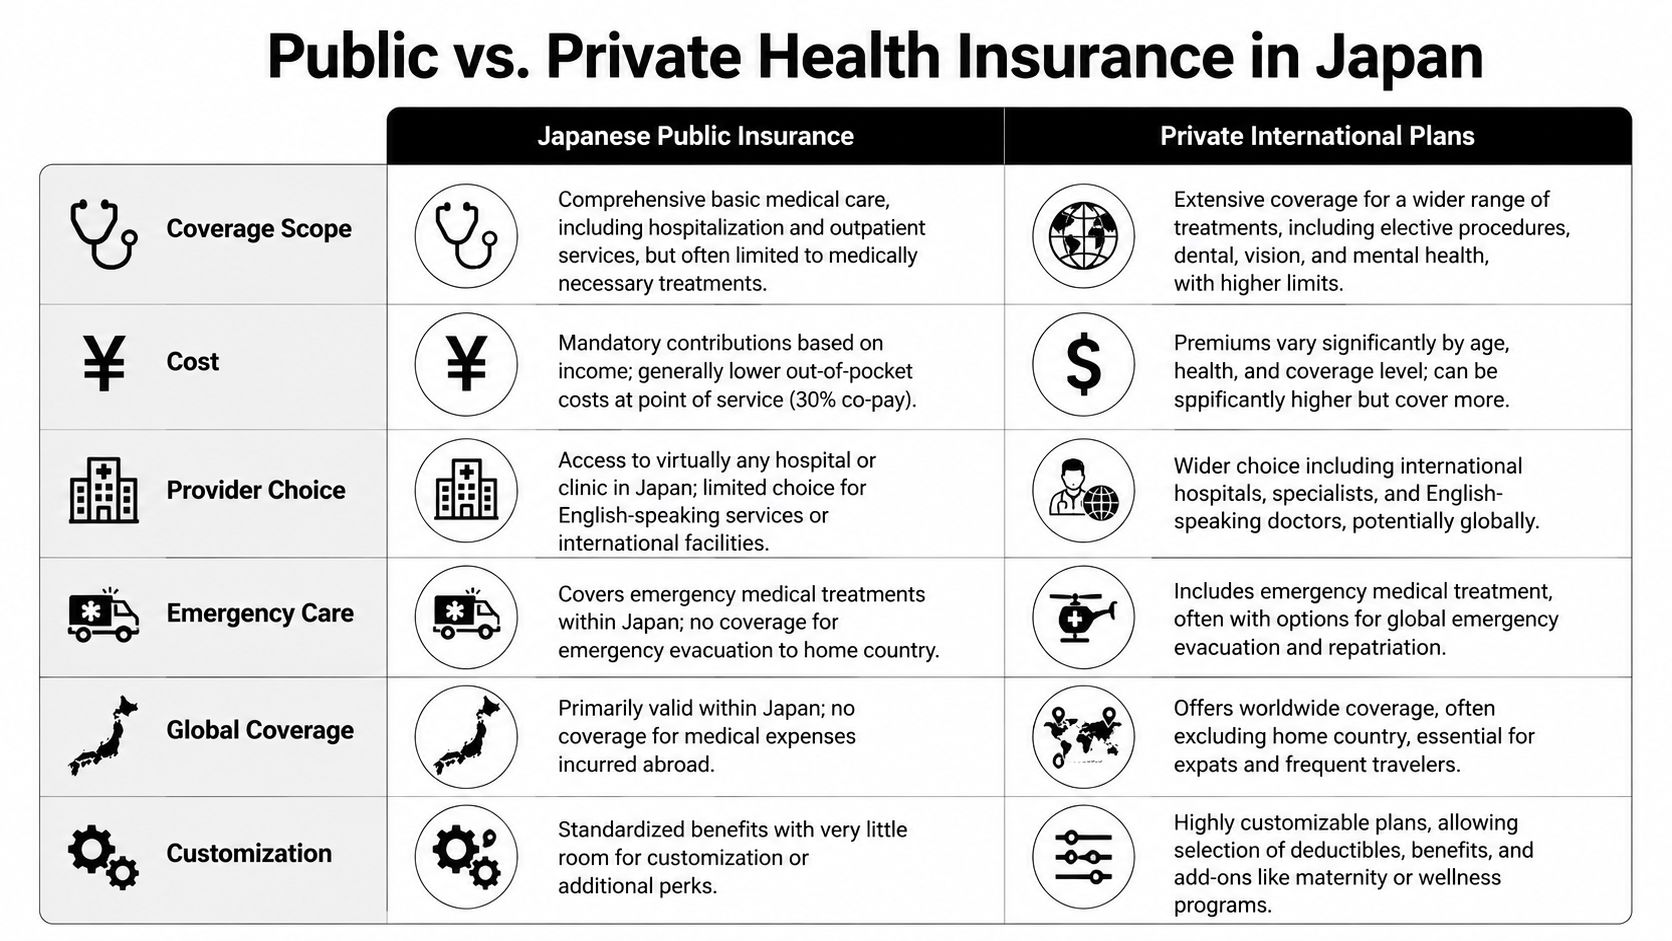
    The Real Comparison: Private Insurance vs NHI Side by Side

    Feature NHI/Shakai Hoken Private International Insurance
    Legal Requirement Mandatory for residents Optional supplement
    Coverage Level 70% of approved treatments 80-100% depending on plan
    Monthly Cost (avg) ¥15,000-¥40,000 ¥20,000-¥80,000+
    English Support Very limited Full English service
    Hospital Choice Any NHI-accepting facility Network hospitals + private
    Private Rooms Not covered Usually covered
    Coverage Outside Japan Very limited Worldwide
    Dental Basic only Optional add-on
    Mental Health Covered at 30% copay Typically covered in full

    How to Choose: A Practical Buying Guide

    Step 1: Understand That NHI Is (Almost) Always Required

    Let me be blunt: if you have a residence card (zairyu card), you are legally required to enroll in either Shakai Hoken through your employer or NHI at your local ward office. Private insurance is in addition to this, not instead of it. The only narrow exception is some company-sponsored expatriate packages where the employer has made special arrangements — but this is rare and getting rarer.

    Step 2: Assess Your Actual Needs

    Ask yourself these questions honestly:

    • How comfortable are you communicating in Japanese at a hospital? If the answer is “not at all,” private insurance with English-speaking hospital networks becomes much more valuable.
    • Do you have any ongoing health conditions? NHI covers these from day one with no exclusions. Private insurance may not.
    • Do you travel frequently outside Japan? NHI offers minimal overseas coverage.
    • Are you planning to have children in Japan? Both systems have gaps, but private maternity add-ons can significantly reduce out-of-pocket costs.
    • What’s your income level? Higher earners pay more for NHI but also benefit more from private insurance’s flat premiums.

    Step 3: Consider the Hybrid Approach

    Most experienced expats I know use a combination: mandatory NHI for everyday healthcare (it’s genuinely good and affordable) plus targeted private insurance for specific concerns. Common combinations include:

    • NHI + domestic cancer insurance: The most popular combo among long-term residents. Cancer insurance from Aflac costs ¥2,000-¥4,000/month and provides substantial payouts if diagnosed.
    • NHI + hospitalization insurance: Covers the cost of private rooms and provides daily cash benefits during hospital stays.
    • NHI + international insurance: For expats who travel frequently or want access to English-speaking medical facilities.

    Step 4: Get Quotes and Compare

    Don’t just pick the first option. Get quotes from at least three providers. For international insurance, compare Cigna Global, Allianz Care, and BUPA Global. For domestic supplemental, look at Aflac, Sony Life, and MetLife Japan.

    Step 5: Check Tax Benefits

    Both NHI premiums and domestic private insurance premiums are partially tax-deductible in Japan. This can reduce your actual cost by 20-30% depending on your tax bracket. International insurance premiums paid to overseas companies generally are not tax-deductible in Japan, which is an important consideration.

    Managing your finances efficiently in Japan goes beyond insurance. If you’re sending money internationally, make sure you’re using a service that won’t eat into your savings — our Wise Japan review covers the best option for international transfers.

    Essential Books and Resources for Understanding Japan’s Healthcare System

    If you want to dive deeper into how healthcare works in Japan, these resources are invaluable:

    Frequently Asked Questions

    Can I opt out of NHI if I have private international health insurance?

    Technically, no. Japanese law requires all residents to be enrolled in public health insurance. Some expats have historically slipped through the cracks, but enforcement has tightened significantly since 2020. If you’re later “caught,” you’ll owe backdated premiums from the date you became a resident — potentially tens of thousands of yen. In 2026, immigration is increasingly checking insurance status during visa renewals. My strong advice: just enroll. NHI is affordable and excellent. Use private insurance as a supplement, not a replacement.

    Is Japan’s public healthcare system actually good enough for expats?

    Honestly? Yes, for most people. Japan’s healthcare system consistently ranks among the top in the world. Wait times are short (you can often see a specialist the same week, sometimes the same day), the quality of care is excellent, and the 30% copay keeps costs remarkably low. I’ve had surgeries, ER visits, MRIs, and specialist consultations through NHI, and I’ve never felt the care was subpar. The main limitation for expats is the language barrier — most healthcare is conducted entirely in Japanese. If that’s a concern, private insurance with access to international clinics can be worth the premium.

    How much does the average expat spend on healthcare in Japan per year?

    With NHI only: most healthy expats spend ¥200,000-¥400,000/year total (premiums + copays for occasional doctor visits). With NHI plus domestic supplemental insurance: add another ¥30,000-¥60,000/year. With NHI plus comprehensive international insurance: the total can reach ¥600,000-¥1,200,000/year or more. For context, the average Japanese person spends around ¥340,000/year on healthcare including premiums and out-of-pocket costs.

    What happens to my health insurance if I lose my job in Japan?

    If you leave a company (voluntarily or involuntarily), you have two options: switch to NHI at your local ward office, or continue your Shakai Hoken for up to two years through “voluntary continuation” (ninni keizoku). With voluntary continuation, you pay the full premium yourself (both the employer and employee portions), but it can still be cheaper than NHI if you had a high salary the previous year, since NHI bases premiums on your prior income. You must apply for voluntary continuation within 20 days of leaving your job. Don’t delay — this deadline is strict.

    Does NHI cover mental health treatment and therapy in Japan?

    Yes, NHI covers psychiatric care and some forms of counseling at the standard 30% copay. There’s also a special program called “Jiritsu Shien Iryo” that reduces the copay to 10% for ongoing mental health treatment — you just need to apply through your local ward office with a doctor’s referral. The challenge for expats is finding therapists who speak English and accept NHI. They exist, particularly in Tokyo and Osaka, but availability is limited. Private insurance can give you access to a broader network of English-speaking mental health professionals, including online therapy options.

    Conclusion: My Honest Recommendation for 2026

    After years of navigating Japan’s healthcare system, here’s what I tell every expat who asks me this question:

    For most expats, NHI alone is genuinely sufficient. Japan’s public healthcare is world-class, affordable, and covers the vast majority of situations you’ll encounter. The High-Cost Medical Expense Benefit means even catastrophic medical events won’t bankrupt you.

    Add domestic supplemental insurance if: you want peace of mind around cancer or hospitalization costs, you plan to stay long-term, or you want the tax deduction benefits. A basic Aflac cancer + medical plan for ¥3,000-¥5,000/month is solid, affordable insurance against worst-case scenarios.

    Add international private insurance if: you need English-language medical support, you travel frequently outside Japan, your employer offers it as a benefit (take it!), or you have specific medical needs that benefit from access to private international facilities.

    Don’t skip NHI regardless of what else you have. It’s the law, it’s a great deal, and it covers pre-existing conditions from day one — something no private insurer will match.

    The Japanese healthcare system is, honestly, one of the best things about living here. Once you’ve experienced walking into a clinic without an appointment, seeing a doctor within 30 minutes, getting an X-ray on the spot, and walking out with prescribed medication — all for under ¥5,000 — you’ll understand why most long-term expats consider NHI one of Japan’s greatest perks.

    Take the time to set up your insurance properly when you arrive, and you’ll have one less thing to worry about as you settle into your new life in Japan. And trust me, there are plenty of other things that’ll need your attention — like figuring out your SIM card situation and about a hundred other logistics that come with the territory.

    Stay healthy out there. Japan’s a wonderful place to live — and an even better place to get sick, if you ever have to.

  • Japan Daily Update — 15 August 2026

    Japan News Digest — Saturday, August 15, 2026

    Your daily update on what’s happening in Japan, curated for expats and travellers. Today’s stories cover workplace wellness, tourism trends, and cultural highlights.

    At Japan’s all-women powerlifting contest, strength is beautiful

    The Strongirls Japan powerlifting group is challenging traditional Japanese beauty standards by celebrating muscular strength and athleticism. For expats navigating Japan’s fitness culture, this growing movement offers inclusive gym communities and a refreshing alternative to mainstream thin-ideal messaging.

    Read full story

    A day in the life of an Asakusa rickshaw driver

    Tokyo’s rickshaw drivers share insights into the physical demands of their iconic job, particularly during summer months. If you’re considering tourism-related work or curious about unique career opportunities in Japan, this profile offers practical perspective on what the role demands.

    Read full story

    Japan companies step up efforts to prevent heatstroke

    With temperatures soaring, Japanese employers are implementing innovative heat-safety measures including adjusted work schedules, cooling stations, and temperature-monitoring stickers. Expats working in Japan should be aware of these evolving workplace protections and know what to expect from their employers during summer months.

    Read full story

    Aespa channels summer cheer in Japanese minialbum

    The K-pop group’s new release “Kiss n Tell” offers a lighter sound for Japanese audiences, marking a notable departure from their usual style. Music fans and cultural observers will find this a snapshot of how international artists adapt content for the Japanese market.

    Read full story

    Overnight stays by foreign guests exceed prepandemic levels in 39 prefectures

    Foreign visitor numbers reached 179.92 million overnight stays in 2025, surpassing 2019 levels by 55.6% across most of Japan. This tourism surge highlights Japan’s renewed appeal to travellers and signals strong economic opportunity in hospitality and service sectors for expats.

    Read full story

    Thai schools step up security after deadly shooting

    While this story focuses on Thailand, it reflects broader regional security concerns that may interest expats living and working across Southeast Asia. Understanding safety measures in neighbouring countries provides helpful context for regional awareness.

    Read full story

    Check back tomorrow for the latest Japan updates.


    Compiled daily from Japan Times and GaijinPot. Updated every morning.

  • Health Insurance for Your First Months in Japan Before NHI: What You Actually Need to Know in 2026

    Health Insurance for Your First Months in Japan Before NHI: What You Actually Need to Know in 2026

    Affiliate Disclosure: This article contains affiliate links. If you purchase through these links, I may earn a small commission at no extra cost to you. I only recommend products and services I’ve personally used or thoroughly researched. Your support helps keep this site running — thank you!

    Introduction: The Insurance Gap Nobody Warns You About

    So you’ve got your visa, your flight is booked, and you’re mentally preparing for life in Japan. Exciting stuff. But here’s something that catches almost every new expat off guard: there’s often a gap between when you arrive in Japan and when your National Health Insurance (NHI) or employer-provided health insurance actually kicks in.

    Maybe you’re arriving a week before your job starts. Maybe your company takes a few weeks to process your enrollment. Maybe you’re coming on a working holiday visa and need to register at city hall before anything happens. Or perhaps you’re arriving as a student and your school’s insurance coordination takes time. Whatever the situation, those first days or weeks without coverage can feel nerve-wracking — especially in a country where you don’t speak the language fluently and a simple clinic visit could cost you ¥5,000-¥15,000 out of pocket.

    I remember my own first week in Tokyo back in 2016. I slipped on wet stairs at Shinjuku Station (classic), twisted my ankle, and had zero insurance coverage. The X-ray and consultation cost me about ¥12,000 — roughly $80 at the time. Not catastrophic, but imagine if it had been something serious. A hospital stay in Japan without insurance can easily run ¥30,000-¥50,000 per night, and emergency surgery? You’re looking at hundreds of thousands of yen.

    The good news is that in 2026, there are several solid options to bridge this gap. Let me walk you through exactly what I recommend, based on years of helping people make this transition smoothly.

    Understanding the NHI Gap: Why It Exists

    Before we dive into solutions, let’s quickly understand why this gap happens. Japan’s healthcare system is excellent — it covers 70% of medical costs for enrolled members — but enrollment isn’t instant.

    Here’s the typical timeline:

    • Day 1-3: You arrive in Japan, go through immigration, receive your residence card
    • Day 3-7: You register at your local ward/city office (必要 — required within 14 days)
    • Day 7-14: If self-employed, freelance, or not immediately covered by an employer, you apply for NHI at the ward office
    • Day 14-30: Your NHI card arrives by mail

    If your employer provides Shakai Hoken (Employee Health Insurance), the timeline depends on your company’s HR department. Some are lightning fast; others… are not. I’ve seen it take anywhere from 3 days to 6 weeks.

    Important 2026 update: Technically, NHI coverage is retroactive to your date of registration at city hall. So if you register on Day 5 and your card arrives on Day 20, you’re theoretically covered from Day 5. But here’s the catch — without that physical card, most clinics will ask you to pay 100% upfront and reimburse you later. That reimbursement process can take weeks, requires Japanese paperwork, and honestly, it’s a headache you don’t need during your first month in a new country.

    That’s why having bridge insurance makes so much sense. Let’s look at the best options.

    SafetyWing Nomad Insurance — Best Overall for Flexibility

    If I could only recommend one option for covering your first months in Japan, SafetyWing would be it. I’ve recommended this to dozens of people moving to Japan, and the feedback has been consistently positive.

    SafetyWing’s Nomad Insurance is specifically designed for people who are traveling or relocating internationally. Unlike traditional travel insurance that requires you to purchase before departure and has strict trip-length limits, SafetyWing works on a subscription model — you can start it anytime, even after you’ve already arrived in Japan.

    Key coverage details for Japan:

    • Up to $250,000 in medical coverage per incident
    • Hospital stays and emergency room visits covered
    • Covers COVID-19 and other infectious diseases
    • Prescription medications included
    • Emergency medical evacuation
    • Starts at approximately $45-$56 per 4-week period (prices vary by age)

    Pros:

    • Can be purchased after arrival — huge advantage
    • Month-to-month subscription, cancel anytime
    • Affordable compared to traditional international health insurance
    • Claims process is straightforward and mostly online
    • Covers you in Japan and if you travel to other countries
    • No network restrictions — use any hospital or clinic

    Cons:

    • $250 deductible per illness/injury (except for certain preventive care)
    • Doesn’t cover pre-existing conditions
    • Dental coverage is limited to emergency situations only
    • Mental health coverage is limited
    • Not a replacement for long-term health insurance

    SafetyWing is perfect for that 1-8 week gap before your NHI or employer insurance activates. You sign up online in about 5 minutes, and coverage starts the next day. When your Japanese insurance kicks in, you simply cancel.

    World Nomads — Best for Adventure-Oriented Arrivals

    If you’re planning to do some serious exploring during your first weeks — hiking in the Japanese Alps, skiing in Hokkaido, surfing in Chiba — World Nomads is worth considering. They specifically cover adventure activities that many other insurers exclude.

    World Nomads offers two plan levels: Standard and Explorer. For Japan, the Explorer plan is worth the extra cost if you plan to be active, as it covers a much wider range of sports and activities.

    Key coverage details:

    • Emergency medical coverage up to $100,000 (Standard) or $300,000 (Explorer)
    • Covers 200+ adventure activities on the Explorer plan
    • Trip interruption and baggage coverage included
    • 24/7 emergency assistance hotline with multilingual support
    • Pricing varies but typically $75-$150 for a 30-day period

    Pros:

    • Excellent adventure sports coverage
    • Can be purchased after you’ve left your home country
    • Strong reputation and established claims process
    • Good emergency assistance for navigating Japanese hospitals

    Cons:

    • More expensive than SafetyWing
    • Coverage periods are less flexible — you buy a set period upfront
    • Some users report slow claims processing
    • Age restrictions apply (typically up to 69)

    Allianz Travel Insurance — Best for Comprehensive Pre-Departure Coverage

    If you’re reading this before your move and want to set everything up in advance, Allianz is a solid traditional travel insurance option. They’re one of the world’s largest insurers, and their travel plans are well-suited for the relocation period.

    The OneTrip Prime or AllTrips Prime plans work well for covering your initial period in Japan. The key advantage of Allianz is their robust network and straightforward claims process.

    Pros:

    • Well-known global brand — Japanese hospitals recognize it
    • Comprehensive emergency medical coverage
    • Includes emergency dental
    • Trip cancellation and interruption benefits are a bonus during relocation
    • Easy to file claims through their app

    Cons:

    • Must be purchased before departure in most cases
    • Less flexible than subscription-based options
    • Can be pricey for longer coverage periods
    • Designed more for travelers than relocators

    Your Home Country’s Travel Insurance — Don’t Overlook What You Might Already Have

    Before you buy anything, check what you might already have. This sounds obvious, but I’ve met so many expats who purchased separate coverage without realizing they were already protected.

    Check these sources:

    • Credit card travel insurance: Many premium credit cards (Chase Sapphire, Amex Platinum, etc.) include travel medical insurance for the first 60-90 days of international travel. Read the fine print — some require you to have purchased your flight with the card.
    • Home country health insurance: Some plans provide limited international coverage. Check with your provider, though be aware that coverage is often very limited abroad.
    • Your employer: If you’re moving to Japan for work, your company may provide coverage from Day 1, even before your Shakai Hoken card arrives. Ask HR specifically about this.
    • University/language school insurance: Many Japanese language schools and universities include basic insurance or can help you enroll in NHI before classes start.

    Travel Medical Kits — Because Prevention Beats Insurance Claims

    While insurance handles the big stuff, having a solid first-aid and medical kit saves you from unnecessary clinic visits for minor issues. Japanese pharmacies are excellent but navigating them in your first weeks — when you can’t read the kanji on medication boxes — is genuinely challenging.

    I always recommend arriving with a personal medical kit that includes familiar medications. You can find well-reviewed travel medical kits on Amazon that cover the basics: pain relievers, antihistamines, bandages, antiseptic, and digestive aids.

    Also consider packing a supply of any OTC medications you rely on. Some common Western medications are either unavailable or sold in much lower doses in Japan. A compact international travel first aid kit is worth the suitcase space.

    Buying Guide: How to Choose the Right Bridge Insurance

    Here’s my step-by-step approach to choosing coverage for your first months in Japan:

    Step 1: Determine Your Gap Period

    Figure out realistically how long you’ll be without Japanese health insurance. If your employer is handling everything and you start work within days of arriving, you might only need 1-2 weeks of coverage. If you’re self-employed or a freelancer, plan for 3-4 weeks minimum.

    Step 2: Assess Your Risk Level

    Be honest with yourself. Do you have any chronic conditions? Are you planning physical activities? Are you arriving during flu season (December-February)? Higher risk = more comprehensive coverage needed.

    Step 3: Check Existing Coverage

    Go through your credit cards, existing insurance policies, and employer benefits before purchasing anything new. You might be surprised.

    Step 4: Choose Your Plan

    • Budget-conscious, low-risk: SafetyWing Nomad Insurance (~$45/month)
    • Adventure-focused: World Nomads Explorer Plan (~$100-150/month)
    • Comprehensive, pre-departure: Allianz OneTrip Prime (varies)
    • Already have credit card coverage: Verify the details and keep your card company’s emergency number saved in your phone

    Step 5: Prepare for Claims

    Regardless of which insurance you choose, do these things before you need medical care:

    • Save your policy number and emergency contact numbers in your phone
    • Download your insurer’s app if available
    • Keep a printed copy of your policy in your bag
    • Know the Japanese emergency number: 119 for ambulance, 110 for police
    • Locate English-speaking hospitals and clinics near your area (Tokyo, Osaka, and other major cities have several)

    For getting settled with other essentials during your first weeks, check out our complete moving to Japan checklist so nothing falls through the cracks.

    What to Do If You Need Medical Care Before Your Insurance Card Arrives

    Even with bridge insurance, navigating the Japanese healthcare system can be daunting. Here’s what to do:

    1. For non-emergencies: Visit a clinic (クリニック, kurinikku) rather than a hospital. They’re faster, cheaper, and many accept walk-ins. Google “English speaking clinic near me” in your area.
    2. For emergencies: Call 119 for an ambulance. Ambulances in Japan are free — yes, free — regardless of insurance status. The hospital treatment is what costs money.
    3. Payment: Most clinics and hospitals will ask you to pay the full amount upfront if you don’t have a Japanese insurance card. Keep receipts for everything — you’ll need them for either your bridge insurance claim or your NHI reimbursement.
    4. Language barrier: The AMDA International Medical Information Center (03-6233-9266) provides free multilingual medical consultation and can help you find appropriate care. Save this number.
    5. Prescriptions: Japanese doctors tend to prescribe medications in smaller quantities. You’ll receive a prescription slip (処方箋) to take to a pharmacy (薬局) near the clinic. The pharmacist will fill it — this is a separate payment from the clinic visit.

    Having a reliable way to communicate and look things up is essential during medical situations. Make sure you have a good SIM card for your phone so you can access translation apps and maps when you need them most.

    Frequently Asked Questions

    Is it legal to be in Japan without health insurance?

    Technically, all residents of Japan with a valid visa (longer than 3 months) are required to enroll in either NHI or employer-provided Shakai Hoken. However, there’s an inherent processing period when you first arrive. You won’t get in trouble for the gap — it’s understood that enrollment takes time. The requirement is that you register at your ward office within 14 days of arrival, which starts the NHI enrollment process. Bridge insurance is for your personal protection during this processing period, not a legal requirement.

    Does NHI cover me retroactively from my arrival date?

    NHI coverage is retroactive to your date of registration at the ward office, not your arrival date. So if you arrive on January 1st and register on January 8th, your NHI technically starts January 8th. However, getting reimbursed for the retroactive period requires submitting receipts to your ward office, filling out Japanese paperwork, and waiting several weeks. Having bridge insurance simplifies everything — you just file a claim with your insurer instead of navigating Japanese bureaucracy during your first month.

    How much does a hospital visit cost in Japan without insurance?

    Without insurance, you’ll pay 100% of medical costs. A basic clinic visit with a consultation typically runs ¥3,000-¥8,000 ($20-$55). Add blood tests and it’s ¥10,000-¥20,000 ($65-$135). An emergency room visit can cost ¥20,000-¥50,000+ ($135-$340+). A hospital stay averages ¥30,000-¥50,000 per night ($200-$340). Surgery costs vary wildly but can easily exceed ¥500,000 ($3,400+). With NHI, you’d only pay 30% of these amounts. This is why bridge insurance is so important.

    Can I use my bridge insurance and then get reimbursed by NHI for the same visit?

    No — this would be double-dipping and isn’t allowed. Use one or the other. If you have bridge insurance and need care before your NHI card arrives, file the claim with your bridge insurer. It’s simpler and faster than the NHI reimbursement process. Once your NHI card arrives and your bridge insurance period ends, switch to using your NHI card for all future visits.

    What about dental care during the gap period?

    Most bridge insurance policies only cover emergency dental (like a broken tooth from an accident), not routine dental care. My advice: get a dental checkup and any needed work done in your home country before moving. If you have a dental emergency during the gap, go to a dentist, pay out of pocket, and file a claim with your bridge insurer if it qualifies as emergency treatment. Once your NHI kicks in, dental is covered at the standard 70% rate, which is one of the great perks of the Japanese system.

    Conclusion: Don’t Skip the Bridge Insurance

    Moving to Japan is one of the most exciting things you’ll ever do. Don’t let a preventable medical bill dampen the experience. The cost of bridge insurance — roughly $45-$150 for a month — is negligible compared to the potential financial exposure of being uninsured, even for a few weeks.

    Here’s my final recommendation for 2026:

    • Most people: Go with SafetyWing. It’s affordable, flexible, and purpose-built for exactly this situation. Sign up before or after you arrive, cancel when your NHI or Shakai Hoken activates.
    • Adventure seekers: World Nomads Explorer plan gives you peace of mind for those Fuji hikes and ski trips.
    • Risk-averse planners: Allianz offers comprehensive coverage from a globally trusted brand.

    Get your insurance sorted, register at your ward office as soon as possible after arrival, and then focus on what you came to Japan for — building an amazing life in one of the world’s most fascinating countries.

    And while you’re getting everything set up, don’t forget to check out our guide on using Wise for money transfers in Japan — because figuring out finances is probably the next thing on your list.

    Stay safe out there, and welcome to Japan. 🇯🇵

  • Japan Daily Update — 14 August 2026

    “`html

    Japan News Digest — Friday, August 14, 2026
    Your daily roundup of news from Japan Times and GaijinPot, curated for expats and travellers in Japan.

    Extreme heat sweeping Japan: Learn the vocabulary

    With temperatures soaring across the country, understanding Japanese heat-related vocabulary can help you navigate summer conversations and stay prepared. From terms for tropical nights to mountain escape destinations, this guide offers practical language for dealing with Japan’s intense summer weather.

    Read full story

    Japan passport applications surge 60% in July

    If you’re planning international travel or considering visa applications, be aware that passport offices are experiencing unprecedented demand with 3.3 times more applications in early July than last year. This surge could impact processing times, so plan ahead if you need documentation renewed.

    Read full story

    Nearly half of Japan supports food tax cut plan

    With nearly 50% public support for reducing consumption tax on food items, changes to Japan’s tax system could affect your grocery bills and dining costs. This growing consensus may signal potential policy shifts that could ease the cost of living for residents and visitors alike.

    Read full story

    Putin’s disputed island visit sparks Tokyo protest

    Geopolitical tensions between Russia and Japan have intensified following a high-profile visit to contested territory off Hokkaido. Expats should stay informed about regional disputes and their potential implications for travel and residency in Japan.

    Read full story

    Beverage makers introduce compact, portable bottles

    Japan’s drink manufacturers are responding to market trends with smaller, easier-to-carry bottle designs that appeal to budget-conscious consumers. If you’re navigating Japan’s convenience store culture, you’ll likely notice more compact options suited to on-the-go consumption.

    Read full story

    Kumamoto Castle reopens after major earthquake

    The famous landmark has reopened just two weeks after a 7.1 magnitude earthquake caused significant damage, showcasing Japan’s rapid disaster response and engineering resilience. If you’re planning a visit to Kumamoto, the castle is now accessible again after comprehensive safety inspections.

    Read full story

    Check back tomorrow for the latest Japan updates.

    “`


    Compiled daily from Japan Times and GaijinPot. Updated every morning.

  • How Much Does a Hospital Visit Cost in Japan Without Insurance in 2026

    How Much Does a Hospital Visit Cost in Japan Without Insurance in 2026

    Affiliate Disclosure: This post contains affiliate links. If you purchase through these links, I may earn a small commission at no extra cost to you. I only recommend products and services I’ve personally used or thoroughly researched during my years living in Japan.

    Introduction: The Bill Nobody Wants to Get

    Let me tell you about the time my friend Jake — a freelance English teacher who’d been in Tokyo for three months — slipped on a wet convenience store floor and broke his wrist. He hadn’t gotten around to enrolling in Japan’s National Health Insurance yet. “How bad could it be?” he thought. The answer: about ¥180,000 (roughly $1,200 USD) for the emergency room visit, X-rays, a cast, and medication. That’s the kind of wake-up call nobody wants.

    If you’re living in Japan, traveling through, or just arrived and haven’t sorted out your insurance situation yet, understanding hospital costs without coverage is absolutely critical. Japan has some of the best healthcare in the world — clean hospitals, skilled doctors, advanced technology — but without insurance, the full sticker price can sting.

    I’ve been helping expats navigate life in Japan for over a decade, and the insurance question is one of the most common things people ask me about. So let’s break down exactly what you can expect to pay out of pocket in 2026, what your options are, and how to protect yourself financially while you’re here.

    Before we dive in, if you’re still in the planning stages of your move, check out our comprehensive moving to Japan checklist — it covers insurance enrollment and a lot more.

    Understanding Japan’s Healthcare System: A Quick Primer

    Japan operates on a universal healthcare model. Every resident — including foreign residents on visas longer than three months — is legally required to enroll in some form of health insurance. This is either Shakai Hoken (Employee Health Insurance, provided through your employer) or Kokumin Kenko Hoken (National Health Insurance/NHI, for self-employed, students, and others).

    When you have insurance, you typically pay only 30% of the total medical bill. The government covers the remaining 70%. That’s an incredible deal, and it’s one of the reasons Japan’s healthcare system is ranked among the best globally.

    But here’s the thing: if you don’t have insurance — whether you’re a short-term tourist, you just arrived and haven’t enrolled yet, or you’ve let your premiums lapse — you’re responsible for 100% of the cost. And Japanese hospitals will absolutely charge you the full amount.

    Actual Hospital Visit Costs in Japan Without Insurance (2026 Breakdown)

    Let’s get into real numbers. These are based on actual medical fee schedules (the Japanese government sets standardized prices for medical procedures), my conversations with expats, and data from hospital billing departments across Japan in 2026.

    General Outpatient Visit (Non-Emergency)

    • Initial consultation fee: ¥2,880–¥5,000 ($19–$33 USD)
    • Basic examination: ¥5,000–¥10,000 ($33–$67 USD)
    • Blood tests: ¥5,000–¥15,000 ($33–$100 USD)
    • Prescription medication (at pharmacy): ¥1,000–¥8,000 ($7–$53 USD)
    • Total typical visit: ¥8,000–¥30,000 ($53–$200 USD)

    Emergency Room Visit

    • ER surcharge (after-hours/holiday): ¥6,000–¥12,000 ($40–$80 USD)
    • Basic treatment + consultation: ¥15,000–¥30,000 ($100–$200 USD)
    • X-rays: ¥4,000–¥10,000 ($27–$67 USD)
    • CT scan: ¥15,000–¥30,000 ($100–$200 USD)
    • MRI: ¥20,000–¥50,000 ($133–$333 USD)
    • Total typical ER visit: ¥30,000–¥100,000+ ($200–$670+ USD)

    Hospitalization

    • Hospital bed per day (shared room): ¥10,000–¥20,000 ($67–$133 USD)
    • Private room surcharge: ¥5,000–¥50,000+ additional per day ($33–$333+ USD)
    • Surgery (minor, e.g., appendectomy): ¥300,000–¥600,000 ($2,000–$4,000 USD)
    • Surgery (major, e.g., cardiac): ¥1,000,000–¥3,000,000+ ($6,700–$20,000+ USD)
    • Childbirth (natural delivery): ¥400,000–¥700,000 ($2,670–$4,670 USD)
    • Childbirth (C-section): ¥600,000–¥1,000,000 ($4,000–$6,700 USD)

    Dental

    • Check-up and cleaning: ¥5,000–¥10,000 ($33–$67 USD)
    • Cavity filling: ¥3,000–¥10,000 ($20–$67 USD)
    • Root canal: ¥20,000–¥60,000 ($133–$400 USD)
    • Tooth extraction: ¥5,000–¥15,000 ($33–$100 USD)

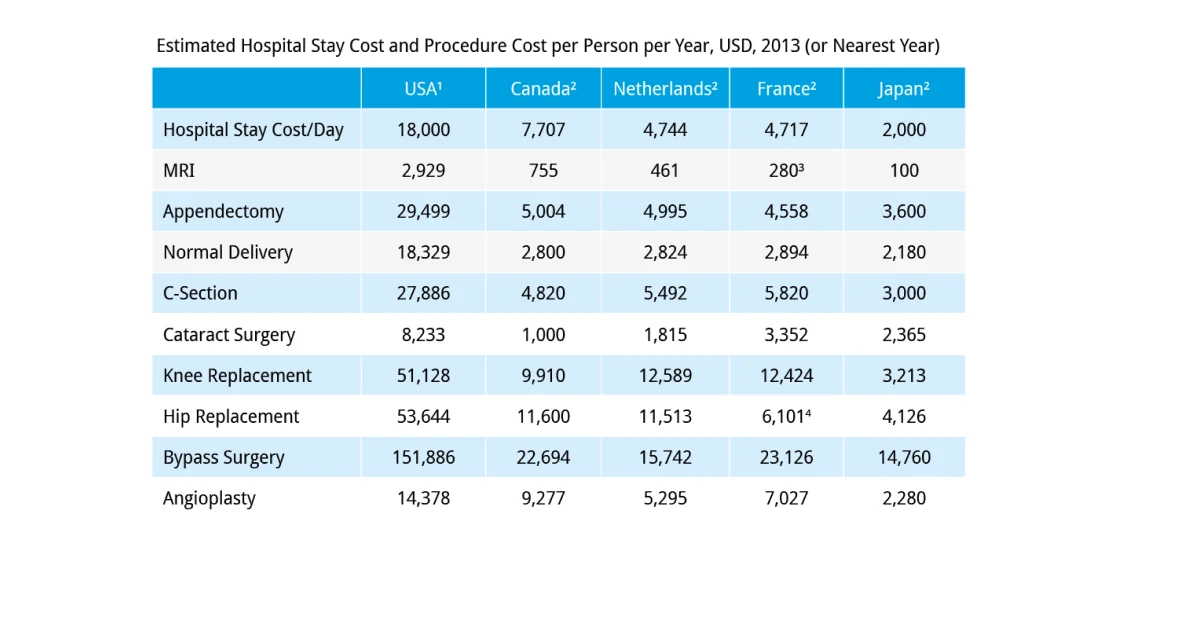
    Important context: Even at full price, these costs are often dramatically lower than equivalent treatments in the United States, where an ER visit can easily cost $2,000–$5,000+ and a simple appendectomy runs $10,000–$35,000. Japan’s standardized fee system keeps prices relatively reasonable even without insurance. But “reasonable” is relative — if you’re on a tight budget, a surprise ¥100,000 bill is no joke.

    Comparison: With Insurance vs. Without Insurance

    Service Without Insurance (100%) With NHI (30%) You Save
    General clinic visit ¥15,000 ¥4,500 ¥10,500
    ER visit with X-ray ¥50,000 ¥15,000 ¥35,000
    3-day hospitalization ¥150,000 ¥45,000 ¥105,000
    Appendectomy ¥500,000 ¥150,000* ¥350,000

    *With NHI, the High-Cost Medical Expense system (Kougaku Ryouyouhi) caps your monthly out-of-pocket expenses even further — often around ¥80,000–¥90,000 per month for average earners. This safety net doesn’t exist for uninsured patients.

    Travel Insurance Options for Short-Term Visitors

    If you’re visiting Japan as a tourist, you won’t be eligible for NHI. Your best protection is travel insurance purchased before your trip. Here are the options I consistently recommend:

    SafetyWing (Nomad Insurance)

    Best for: Digital nomads and long-term travelers

    Cost: Starting around $45–$55/month in 2026

    Pros:

    • Can be purchased while already abroad
    • Month-to-month subscription model — no long-term commitment
    • Covers hospital visits, emergencies, and some outpatient care
    • Works in 180+ countries including Japan

    Cons:

    • Deductible of $250 per incident
    • Doesn’t cover pre-existing conditions
    • Coverage limits may be low for major surgery

    World Nomads

    Best for: Short-term tourists and adventure travelers

    Cost: Varies by trip length, typically $100–$300 for a 2-week trip

    Pros:

    • Excellent emergency medical coverage (up to $100,000+)
    • Can purchase and extend while traveling
    • Covers adventure activities (skiing in Niseko, hiking Mt. Fuji)

    Cons:

    • More expensive than SafetyWing for long trips
    • Claims process can be slow

    Your Country’s Travel Insurance

    Many countries offer affordable travel insurance through domestic providers. Always check if your credit card includes travel medical coverage — some premium cards offer this automatically when you book flights with the card.

    How to Enroll in Japan’s National Health Insurance (For Residents)

    If you’re a resident of Japan (meaning you have a residence card with a stay of 3+ months), you’re legally required to enroll in health insurance. Here’s how:

    1. Visit your local ward office (kuyakusho/shiyakusho) within 14 days of moving to your address
    2. Bring your residence card (zairyu card) and passport
    3. Fill out the application form — staff can help, and many offices have English-speaking support or multilingual forms
    4. Receive your insurance card — usually issued on the spot or mailed within 1-2 weeks
    5. Pay your premiums — billed monthly or quarterly, based on your previous year’s income

    Cost of NHI premiums: For newcomers with no prior Japanese income, expect to pay around ¥15,000–¥25,000 per month ($100–$167 USD). This varies by municipality. It might feel like a lot, but compared to one uninsured hospital visit, it pays for itself almost immediately.

    Pro tip: If you’ve been in Japan without insurance and enroll late, you may be required to pay back premiums from your enrollment date (the date you became eligible, not the date you walk into the office). Don’t let this deter you — it’s still worth doing.

    What Happens If You Can’t Pay Your Hospital Bill

    Japanese hospitals will not refuse emergency treatment due to inability to pay — this is required by law. However, they will absolutely pursue payment afterward. Here’s what typically happens:

    • You’ll receive itemized bills — Japanese medical billing is remarkably transparent
    • Payment plans are sometimes available — ask the hospital’s accounting department (kaikei madoguchi)
    • Unpaid bills can affect your visa renewal — immigration authorities are increasingly checking for unpaid medical debts
    • Collection agencies may get involved — though this is less aggressive than in the US

    Bottom line: always try to settle your bills. If you’re struggling, communicate with the hospital — they’re often more flexible than you’d expect.

    Essential Items for Managing Healthcare in Japan

    Having the right tools makes navigating Japanese healthcare much easier, especially when language is a barrier. Here are my top recommendations:

    A Reliable Translation App

    Google Translate with its camera function is a lifesaver for reading medical forms, prescription labels, and hospital signage. For deeper language study that’ll help you communicate symptoms to doctors, check out our guide to the best language apps for Japanese.

    A Good Portable Battery Pack

    Hospital waits in Japan can be long (2-4 hours is normal at large hospitals). Keep your phone charged so you can use translation apps, contact your embassy, or look up medical terminology.

    Browse portable chargers on Amazon →

    A Medical Translation Card or Booklet

    English-Japanese medical phrase books are incredibly useful in emergency situations when your phone might not be accessible or you’re too stressed to type.

    Find Japanese-English medical references on Amazon →

    A Document Organizer

    Keep your insurance card, residence card, prescriptions, and medical records organized. Japanese hospitals often ask for your insurance card and diagnosis record booklet (okusuri techo for medications) at every visit.

    Check out travel document organizers on Amazon →

    Money-Saving Tips for Healthcare in Japan

    Whether you have insurance or not, these tips can help you save money on medical care:

    • Visit clinics (shinryoujo) instead of hospitals: Large hospitals charge an additional fee (¥5,000–¥7,000) if you visit without a referral. Go to a small local clinic first, and they’ll refer you if needed.
    • Go during regular hours: After-hours, weekend, and holiday surcharges can add ¥3,000–¥12,000 to your bill.
    • Use generic medications: Ask the pharmacist for “generic” (jenericku) — they’re significantly cheaper and readily available in Japan.
    • Get a medication notebook (okusuri techo): Pharmacies give these out for free. They track your prescriptions and help prevent duplicate or conflicting medications, saving you money and keeping you safe.
    • Use a Wise account for currency management: If you’re paying medical bills from overseas funds, you’ll want the best exchange rates. Check out our Wise Japan review for why it’s the go-to financial tool for expats.

    Buying Guide: Choosing the Right Insurance Coverage in Japan

    Here’s a framework for deciding what coverage you need:

    If You’re a Tourist (Under 90 Days)

    Get travel insurance before you arrive. Period. Even a basic policy costing $50–$100 can save you thousands. Japan’s tourist visa doesn’t qualify you for NHI, so private coverage is your only option.

    If You’re a New Resident (First 3 Months)

    Enroll in NHI at your ward office immediately upon registering your address. Don’t wait. The coverage is retroactive to your registration date, but you need the card in hand to use the 30% copay rate at hospitals.

    If You’re Employed

    Your employer should enroll you in Shakai Hoken automatically. Confirm this during your onboarding. The premiums are split 50/50 between you and your employer, and coverage is generally more comprehensive than NHI.

    If You Want Extra Coverage

    Many expats supplement their Japanese insurance with private policies for things like:

    • English-speaking hospital access
    • Repatriation coverage
    • Higher coverage limits for surgery and hospitalization
    • Dental and vision (not fully covered by NHI)

    Frequently Asked Questions

    Can I see a doctor in Japan without insurance?

    Yes, absolutely. No hospital or clinic in Japan will turn you away for lack of insurance, especially in emergencies. You’ll simply be charged the full cost (100%) of treatment instead of the subsidized 30% that insured patients pay. Walk-in clinics are widely available, and many in major cities like Tokyo and Osaka have English-speaking staff. Just be prepared to pay the full bill at the counter or billing window before you leave — most clinics expect same-day payment for uninsured patients.

    Is healthcare in Japan expensive without insurance compared to other countries?

    Compared to the United States, Japan’s uninsured healthcare costs are remarkably affordable. A general doctor’s visit that might cost $200–$500 in the US will typically run ¥8,000–¥30,000 ($53–$200) in Japan. Emergency room visits, surgeries, and hospitalizations are similarly lower. However, compared to countries like Thailand or the Philippines, Japan is on the pricier side. The quality of care, though, is consistently world-class — you’re getting excellent value even at full price.

    What should I do if I have a medical emergency in Japan and have no insurance?

    Call 119 (Japan’s emergency number for ambulance and fire). Ambulance rides in Japan are completely free — yes, free — regardless of your insurance status. This is one of the amazing things about Japan’s system. The ambulance will take you to the nearest available hospital. Focus on getting treated first, then deal with the bill afterward. Hospitals will work with you on payment. Also contact your country’s embassy — they can sometimes assist with emergency medical situations and help arrange payment or repatriation if needed.

    Can I enroll in Japanese health insurance retroactively?

    Yes, but with a catch. When you enroll in NHI, your coverage technically starts from the date you became eligible (usually your residence registration date), and you’ll be required to pay all premiums from that date. The good news is that you can then have previous medical bills recalculated at the 30% insured rate — but this process requires submitting receipts and paperwork, and not all hospitals make it easy. The lesson: enroll as soon as possible to avoid the hassle.

    Do Japanese hospitals accept credit cards?

    Large hospitals generally accept major credit cards (Visa, Mastercard, and sometimes American Express). However, smaller clinics and some pharmacies may be cash-only. Always carry at least ¥20,000–¥30,000 in cash when visiting a medical facility, just in case. Some hospitals also accept payment via IC cards (Suica/Pasmo) or QR code payment apps like PayPay, but don’t count on it for medical billing.

    Conclusion: Don’t Gamble With Your Health (or Your Wallet)

    Look, I get it. When you’re caught up in the excitement of moving to Japan — finding an apartment, exploring neighborhoods, figuring out how the trains work — health insurance feels like boring paperwork that can wait. But trust me, after watching dozens of expat friends get hit with unexpected medical bills, I can tell you it’s one of the first things you should sort out.

    The numbers don’t lie: a single hospital visit without insurance can cost anywhere from ¥8,000 for a simple consultation to well over ¥1,000,000 for surgery. With Japan’s National Health Insurance, those same bills drop to just 30% of the total — and the high-cost medical expense system caps your monthly out-of-pocket even further.

    If you’re a tourist, get travel insurance before you board the plane. If you’re a new resident, walk into your ward office and sign up for NHI this week. If you’re employed, confirm your Shakai Hoken enrollment with your HR department tomorrow. The peace of mind is worth every yen of those monthly premiums.

    Japan’s healthcare system is one of the best things about living here — affordable, high-quality, and accessible. Don’t miss out on it by being uninsured. Your future self (and your bank account) will thank you.

    Have questions about healthcare costs in Japan or need help navigating the insurance system? Drop a comment below — I’ve been through it all and I’m happy to help.

  • Japan Daily Update — 13 August 2026

    Japan News Digest — Thursday 13 August 2026
    Your daily update on stories affecting expats and travelers in Japan, covering politics, currency markets, travel safety, and lifestyle trends.

    Takaichi unlikely to visit Yasukuni Shrine on war anniversary

    Prime Minister Sanae Takaichi’s decision to skip the controversial Yasukuni Shrine visit signals Japan’s careful diplomatic balancing act with neighboring countries. If you’re traveling in East Asia or engaging with regional communities in Japan, understanding these geopolitical sensitivities can help you navigate cultural conversations more respectfully.

    Read full story

    Mexican man arrested over attempt to smuggle 200 lizards into Japan

    Wildlife smuggling remains a serious customs concern at Japanese airports, with authorities actively enforcing strict import regulations. This reminder is particularly relevant if you’re planning to bring pets or animals into Japan—always verify regulations well in advance to avoid legal trouble.

    Read full story

    Intervention and higher rates might not be enough to stop yen from weakening

    Japan’s currency continues its downward trajectory despite government intervention efforts, affecting your purchasing power and cost of living calculations. Expats on fixed salaries should monitor exchange rates carefully, as the weak yen impacts everything from rent adjustments to grocery bills.

    Read full story

    Bessent-Takaichi split on BOJ risks undermining joint yen rescue

    Disagreement between U.S. and Japanese leadership on interest rate policy creates uncertainty in financial markets affecting currency stability. If you’re managing finances across Japan and other countries, this policy disagreement adds another layer of unpredictability to exchange rate planning.

    Read full story

    More young people in Japan undergoing cosmetic surgery

    The rising trend in cosmetic procedures among younger Japanese reflects evolving beauty standards and accessible treatment options. If you’re planning cosmetic procedures in Japan, be aware of the growing medical tourism infrastructure, though always research clinics thoroughly first.

    Read full story

    New ‘Katsu Curry Index’ aims to show how weak the yen really is

    A creative new economic indicator using katsu curry prices provides a practical measure of how currency weakness actually affects dining costs for expats in Japan. This lighthearted index is a useful reminder to track your everyday meal expenses when budgeting for life in Japan.

    Read full story

    Check back tomorrow for the latest Japan updates.


    Compiled daily from Japan Times and GaijinPot. Updated every morning.

  • How Does the Japanese Healthcare System Work for Expats? Your Complete 2026 Guide

    How Does the Japanese Healthcare System Work for Expats? Your Complete 2026 Guide

    Affiliate Disclosure: This article contains affiliate links. If you click through and make a purchase, I may earn a small commission at no extra cost to you. I only recommend products and services I’ve personally used or thoroughly researched. Thanks for supporting the site!

    Introduction: Japan’s Healthcare System Is Better Than You Think

    Let me tell you something that surprised me when I first moved to Japan: the healthcare system here is genuinely excellent — and as an expat, you’re not just allowed to use it, you’re required to. That might sound intimidating, but trust me, once you understand how it works, you’ll realize it’s one of the biggest perks of living in Japan.

    Japan consistently ranks among the top countries in the world for healthcare quality, life expectancy, and affordability. The World Health Organization has repeatedly praised Japan’s universal coverage model. And here’s the kicker — as a foreign resident, you get access to the exact same system Japanese citizens use. No separate “expat tier.” No exclusions for pre-existing conditions. The same doctors, the same hospitals, the same coverage.

    But navigating a healthcare system in a foreign language, with different procedures, unfamiliar insurance cards, and those tiny neighborhood clinics that look like someone’s house? That’s where things get confusing. I’ve been through it all — from the initial enrollment paperwork to emergency room visits at 2 AM where nobody spoke English. This guide covers everything you need to know about the Japanese healthcare system as an expat in 2026, including how to enroll, what it costs, how to find English-speaking doctors, and whether you need supplemental insurance.

    If you’re still in the planning stages of your move, check out our comprehensive moving to Japan checklist to make sure you’ve covered all the basics before arrival.

    Japan’s Two Public Health Insurance Systems: Which One Are You In?

    Japan has universal healthcare, meaning everyone living in the country legally must be enrolled in one of two public health insurance programs. You don’t get to choose — your employment status determines which one you’re in.

    1. Employees’ Health Insurance (Shakai Hoken / 社会保険)

    If you work for a company in Japan — whether you’re teaching English, working in IT, or employed at a Japanese corporation — you’ll be enrolled in Shakai Hoken (Employees’ Health Insurance). This is the more comprehensive of the two options.

    How it works:

    • Your employer handles enrollment — you don’t need to do anything at city hall
    • Premiums are split roughly 50/50 between you and your employer
    • Premiums are automatically deducted from your paycheck (typically 9-10% of your salary, with your employer paying half)
    • Includes health insurance AND pension contributions
    • Covers dependents (spouse, children) at no additional premium cost
    • Includes maternity benefits, injury/sickness allowance, and funeral grants

    2. National Health Insurance (Kokumin Kenko Hoken / 国民健康保険)

    If you’re self-employed, freelancing, studying, or between jobs, you’ll enroll in Kokumin Kenko Hoken (NHI). You sign up at your local ward or city office (区役所 / 市役所).

    How it works:

    • You must enroll yourself at city hall within 14 days of getting your residence card
    • You pay the full premium yourself (no employer contribution)
    • Premiums are based on your previous year’s income, number of dependents, and municipality
    • Premiums vary significantly by city — Tokyo tends to be more expensive than rural areas
    • Does NOT include pension (you enroll in National Pension separately)
    • Dependent coverage requires additional premiums

    Quick Comparison

    Feature Shakai Hoken (Employee) Kokumin Kenko Hoken (NHI)
    Who enrolls Company employees Self-employed, freelancers, students
    Enrollment Employer handles it You go to city hall
    Cost sharing 50/50 with employer You pay 100%
    Dependent coverage Free for dependents Additional premiums per dependent
    Extras Maternity, sickness allowance Basic coverage only
    Typical monthly cost ¥15,000–¥40,000 (your share) ¥5,000–¥60,000+ depending on income

    What Does Japanese Health Insurance Actually Cover?

    Both public insurance systems cover 70% of most medical costs. You pay the remaining 30% out of pocket. For children and elderly patients, the co-pay is even lower (typically 20%).

    Covered services include:

    • Doctor consultations and examinations
    • Prescription medications
    • Surgery and hospitalization
    • Mental health treatment
    • Maternity care (though normal delivery is not covered — it’s not considered a “medical procedure”)
    • Dental care (basic treatments)
    • Rehabilitation
    • Most diagnostic tests (blood work, X-rays, MRIs, etc.)

    Not typically covered:

    • Cosmetic procedures
    • Normal childbirth (though a lump-sum birth allowance of ¥500,000 is provided)
    • Advanced dental work (implants, cosmetic orthodontics)
    • Some cutting-edge treatments and experimental drugs
    • Private hospital rooms (you pay the upgrade difference)
    • Annual health checkups (though many employers and municipalities offer free ones)

    Here’s something most expats don’t realize: Japan has a High-Cost Medical Care system (Kogaku Ryoyo-hi) that caps your monthly out-of-pocket expenses. If your 30% co-pay exceeds a certain threshold (usually around ¥80,000–¥100,000/month depending on income), the government covers the rest. This means even major surgery or extended hospitalization won’t bankrupt you. It’s genuinely one of the best safety nets I’ve seen in any country.

    How Much Does Healthcare Actually Cost in Japan? Real-World Examples

    Let me share some real numbers from my experience and from expat friends in 2026. These are the amounts you pay after insurance (your 30% co-pay):

    • General doctor visit (cold/flu): ¥1,000–¥3,000 ($7–$20 USD)
    • Specialist consultation: ¥2,000–¥5,000 ($14–$35 USD)
    • Prescription medications (1-2 weeks): ¥500–¥2,000 ($3.50–$14 USD)
    • Dental cleaning: ¥2,000–¥4,000 ($14–$28 USD)
    • MRI scan: ¥5,000–¥8,000 ($35–$55 USD)
    • Emergency room visit: ¥5,000–¥15,000 ($35–$100 USD)
    • Childbirth (cesarean): Covered by insurance; normal delivery costs ¥400,000–¥600,000 but the ¥500,000 lump-sum grant offsets most of it

    If you’re coming from the United States, you’ll probably cry tears of joy at these numbers.

    Finding English-Speaking Doctors and Hospitals in Japan

    This is probably the biggest concern for most expats, and I get it. Being sick is stressful enough without a language barrier. Here’s the good news: finding English-speaking medical care is very doable, especially in major cities.

    Resources for finding English-speaking doctors:

    • AMDA International Medical Information Center: A free multilingual helpline that connects you with medical interpreters and English-speaking facilities
    • Japan Healthcare Info (JNTO): The official tourism organization maintains a database of medical facilities with foreign language support
    • Your embassy: Most embassies maintain lists of English-speaking doctors near their location
    • Himawari (Tokyo Metropolitan Health Medical Information Center): Tokyo’s official multilingual medical consultation service
    • Hospital websites: Major hospitals like St. Luke’s International Hospital (Tokyo), Kobe Adventist Hospital, and JCHO Osaka Hospital have dedicated international departments

    Pro tips from personal experience:

    • International clinics exist in Tokyo, Osaka, Nagoya, and Fukuoka — they’re pricier but fully English-speaking
    • Many younger Japanese doctors speak functional English, even at regular clinics
    • Bring a translation app or printed symptoms list in Japanese — it helps enormously at neighborhood clinics
    • University hospitals tend to have better English support than small clinics
    • Consider learning basic medical Japanese — it’s a life skill that pays dividends

    Speaking of language tools, having a solid Japanese language app on your phone can be a literal lifesaver in medical situations. Check out our guide to the best language apps for learning Japanese.

    Do You Need Private or Supplemental Health Insurance in Japan?

    This is a question I get constantly, and the honest answer is: probably not, but maybe. Let me explain.

    When Public Insurance Is Enough

    For most expats, Japan’s public health insurance is comprehensive enough. The 30% co-pay is manageable, the high-cost medical care cap protects you from catastrophic bills, and the coverage is broad. If you’re generally healthy and living in a city with good medical access, you’re well covered.

    When Supplemental Insurance Makes Sense

    • You want a private room during hospitalization — Japanese hospital rooms often have 4-6 beds; private rooms cost ¥5,000–¥30,000+ extra per night
    • You travel outside Japan frequently — Japanese public insurance only covers care within Japan
    • You want coverage for advanced dental or vision care
    • You’re planning pregnancy — supplemental maternity insurance can cover additional costs
    • You want English-language support and medical concierge services
    • You’re concerned about evacuation coverage — getting transported to your home country for treatment if needed

    Recommended Supplemental Insurance Options for 2026

    For international coverage while based in Japan:

    • SafetyWing Nomad Insurance: Affordable option for remote workers; covers you globally with Japan as your base
    • Cigna Global: Comprehensive international plans with strong Japan networks
    • Allianz Care: Flexible plans with English support and direct billing at major hospitals

    For Japanese supplemental insurance (共済/kyosai or 民間保険/minkan hoken):

    • CO-OP Kyosai: Very affordable supplemental plans (as low as ¥2,000/month) popular among residents
    • Aflac Japan: Cancer and medical supplemental insurance — they’re everywhere in Japan for a reason
    • Sony Life / Zurich: English-friendly insurers offering supplemental medical plans for foreign residents

    Essential Items for Managing Healthcare in Japan

    Having the right tools makes navigating Japanese healthcare much smoother. Here are items I recommend every expat have:

    Japanese-English Medical Dictionary — A physical pocket reference is invaluable when your phone dies or you’re in a no-signal basement clinic. Browse Japanese-English medical dictionaries on Amazon.

    Insurance Card Holder / Passport Wallet — Your Japanese insurance card (hokensho) is a physical card you must carry to every appointment. A good cardholder keeps it safe alongside your residence card. Find passport wallets and card holders on Amazon.

    Portable Thermometer — Japanese clinics and hospitals will ask your temperature at every visit (this became even more standard post-COVID). Having your own thermometer for pre-visit checks is smart. Shop digital thermometers on Amazon.

    Medicine Organizer for Japanese Prescriptions — Japanese pharmacies give you medications in individual packets, often multiple types for different times of day. A pill organizer keeps everything straight. Check out pill organizers on Amazon.

    How to Use the Japanese Healthcare System: A Step-by-Step Guide

    Step 1: Get Enrolled in Health Insurance

    If employed, your company handles this. If self-employed or freelancing, visit your local city/ward office with your residence card within 14 days of registering your address. You’ll fill out a form, and they’ll mail your insurance card (hokensho) within 1-2 weeks.

    Step 2: Get Your Insurance Card

    Your hokensho (保険証) is your golden ticket. Starting in 2024, Japan began transitioning to linking health insurance with the My Number card system. By 2026, many facilities accept your My Number card directly, but carrying your traditional insurance card as backup remains wise.

    Step 3: Find a Clinic or Hospital

    Japan’s healthcare system is built around small neighborhood clinics (診療所/shinryojo) for primary care and larger hospitals for specialized treatment. You generally don’t need a referral to see a specialist, but going to a large hospital without a referral from a clinic may incur an extra fee (¥5,000–¥7,000).

    Step 4: Visit the Doctor

    Walk-in appointments are common at clinics — many don’t take reservations. Arrive, hand over your insurance card at reception, fill out a brief questionnaire (often in Japanese, though larger clinics may have English versions), and wait. Wait times can be long, especially at popular clinics.

    Step 5: Pay Your Co-Pay

    After your appointment, you pay your 30% co-pay at the reception desk. Most clinics accept cash only, though this is gradually changing. Some larger hospitals accept credit cards.

    Step 6: Get Your Prescription Filled

    The doctor gives you a prescription slip (処方箋/shohousen). Take it to any pharmacy (調剤薬局/chouzai yakkyoku) — there’s usually one right next to the clinic. Pay your 30% co-pay for the medications.

    A quick note about managing your finances for medical expenses and everything else in Japan: having a good way to transfer money and manage currency is essential. Our Wise Japan review covers the best option for handling international money transfers.

    Pros and Cons of Japan’s Healthcare System for Expats

    Pros

    • Affordable: Even without insurance adjustments, Japanese medical care costs a fraction of what it does in the US, UK private care, or Australia
    • Universal: No pre-existing condition exclusions, no coverage denials
    • High quality: Japan has more MRI and CT machines per capita than almost any country; technology is cutting-edge
    • Accessible: Clinics are everywhere — even tiny towns have multiple options
    • Catastrophic protection: The high-cost medical care cap prevents financial ruin
    • Prescription drugs are cheap: Japan aggressively negotiates drug prices
    • Fast service for diagnostics: Getting an MRI or blood work done often takes days, not weeks or months

    Cons

    • Language barrier: Most neighborhood clinics operate entirely in Japanese
    • Short consultations: Doctors often spend only 3-5 minutes with patients — it can feel rushed
    • Over-prescription tendency: Japanese doctors sometimes prescribe 4-5 medications for a common cold
    • Mental health stigma: While improving, mental healthcare still carries stigma and English-speaking therapists are limited
    • Cash-heavy system: Many clinics still only accept cash payment
    • Waiting times: Popular clinics can have 1-2 hour waits, especially during flu season
    • Dental coverage is basic: Cosmetic and advanced dental work gets expensive fast

    Frequently Asked Questions

    Can I use my home country’s health insurance in Japan?

    Generally, no. Your home country’s insurance (including most travel insurance policies) won’t be accepted at Japanese medical facilities for direct billing. You’re legally required to enroll in Japan’s public health insurance system if you’re a resident. Even if you maintain private international insurance, you’ll still need to be enrolled in either Shakai Hoken or NHI. Some international insurers like Cigna Global do offer direct billing at select Japanese hospitals, but this supplements rather than replaces your mandatory Japanese coverage.

    What happens if I get sick before my insurance card arrives?

    You can still see a doctor. You’ll pay the full cost upfront (100%), then apply for reimbursement at your city hall or through your employer once your insurance is active. Keep all receipts. The insurance will reimburse 70% retroactively. This is common for newly arrived expats, so clinics are used to handling it. Just explain the situation at reception — even basic Japanese like “hoken ga mada desu” (insurance not yet) works.

    Is mental healthcare covered by Japanese health insurance?

    Yes, psychiatric and psychological treatment is covered under Japan’s public health insurance at the standard 30% co-pay rate. Additionally, Japan offers a Jiritsu Shien Iryo (自立支援医療) program that reduces the co-pay to 10% for ongoing mental health treatment. You can apply for this at your city hall with a doctor’s diagnosis. Finding English-speaking psychiatrists and therapists is challenging but possible in major cities. Online therapy platforms that serve Japan-based expats have also expanded significantly by 2026.

    Do I lose my Japanese health insurance if I lose my job?

    No, but you need to switch systems. If you leave your employer, you have 14 days to either enroll in NHI at city hall or opt to continue your Shakai Hoken coverage voluntarily for up to 2 years (called “ninii keizoku” / 任意継続). The voluntary continuation means you pay both the employee and employer portions, so your premium roughly doubles. For most people, switching to NHI is cheaper, especially if your income was modest. Don’t let coverage lapse — gaps can result in back-payments and penalties.

    Can I see a doctor on weekends or holidays in Japan?

    Regular clinics are typically closed on Sundays and national holidays, and many close Saturday afternoons. However, every municipality operates a holiday/emergency clinic (休日診療所/kyujitsu shinryojo) for non-emergency care on these days. For true emergencies, hospital emergency rooms operate 24/7. You can call #7119 (available in many prefectures) for medical consultation to determine whether you need emergency care. The 119 number calls an ambulance, which is free in Japan — but please only use it for genuine emergencies.

    Conclusion: Japan’s Healthcare System Is One of the Best Reasons to Live There

    After years of living in Japan and navigating the healthcare system through everything from routine check-ups to emergency situations, I can honestly say it’s one of the best things about being an expat here. The combination of low costs, high quality, universal access, and catastrophic cost protection creates a system that genuinely takes care of people.

    Yes, the language barrier is real, and yes, you might find the short consultation times frustrating if you’re used to Western-style doctor visits. But the trade-off — being able to walk into almost any clinic without an appointment, see a doctor the same day, get an MRI within the week, and pay less than the cost of a nice dinner — is remarkable.

    Here’s my practical advice for expats in 2026: enroll in your mandatory public insurance immediately upon arrival, download a medical translation app, save the numbers for English-speaking clinics near you, and consider supplemental insurance only if you have specific needs that the public system doesn’t cover well. For 95% of situations, the public system has you covered — literally and figuratively.

    Your health is your most important asset as an expat. Japan’s system makes protecting it surprisingly easy and affordable. Take advantage of it.

  • Japan National Health Insurance Explained for Foreigners (2026 Guide)

    Japan National Health Insurance Explained for Foreigners (2026 Guide)

    Affiliate Disclosure: This article contains affiliate links. If you make a purchase through these links, I may earn a small commission at no extra cost to you. I only recommend products and services I’ve personally used or thoroughly researched. Thanks for supporting the site!

    Introduction: Why Japan’s Health Insurance System Is Actually Amazing (Once You Understand It)

    Let me be honest with you — when I first moved to Japan, the whole health insurance thing confused the hell out of me. I walked into my local ward office, was handed a stack of forms entirely in Japanese, and left feeling more lost than when I arrived. But here’s the thing: once you understand how Japan’s National Health Insurance (NHI) works, you’ll realize it’s one of the best perks of living in this country.

    Japan consistently ranks among the top healthcare systems in the world. We’re talking about a system where you can walk into almost any clinic or hospital, see a doctor — often the same day — and pay only 30% of the bill. No referrals needed. No waiting months for an appointment. No surprise $50,000 bills showing up in your mailbox.

    But as a foreigner, the enrollment process, premium calculations, and coverage details can feel like navigating a maze blindfolded. That’s exactly why I wrote this guide. Whether you’re planning your move or you’ve already landed and are trying to figure things out, I’ll walk you through everything you need to know about Japan’s National Health Insurance in 2026 — in plain English, with real-world advice from someone who’s been through it.

    If you’re still in the planning stages, make sure to check out our comprehensive moving to Japan checklist to make sure health insurance is just one of many boxes you’ve already ticked.

    How Japan’s Health Insurance System Works: The Two Main Types

    Before we dive into NHI specifically, you need to understand that Japan has two main types of public health insurance. Which one you end up on depends entirely on your employment situation.

    1. Employees’ Health Insurance (Shakai Hoken / 社会保険)

    If you work for a company with five or more employees (and increasingly, even smaller companies), you’ll be enrolled in Shakai Hoken. This is the employer-sponsored social insurance program. Your company handles enrollment, and premiums are split roughly 50/50 between you and your employer. It’s deducted automatically from your paycheck, so you barely have to think about it.

    Shakai Hoken also bundles in your pension contributions, which is a separate (and equally confusing) topic for another day.

    2. National Health Insurance (Kokumin Kenko Hoken / 国民健康保険)

    This is what this article focuses on. NHI is for everyone who isn’t covered by employer-sponsored insurance. That includes:

    • Self-employed individuals and freelancers
    • Students
    • Unemployed residents
    • Part-time workers not eligible for Shakai Hoken
    • Retirees
    • Dependents not covered under a spouse’s employer plan

    The key rule: If you’re a registered resident of Japan with a valid visa of three months or longer, you are legally required to have health insurance. This isn’t optional. Japan has universal healthcare, and “universal” means everyone — including you.

    How to Enroll in Japan’s National Health Insurance

    Enrollment happens at your local city or ward office (市役所 / shiyakusho or 区役所 / kuyakusho). Here’s the step-by-step process:

    Step 1: Register Your Address

    When you first arrive in Japan and register your address at the ward office (which you must do within 14 days of moving in), the staff will typically ask about your health insurance status. If you’re not covered by an employer, they’ll guide you to the NHI counter right then and there.

    Step 2: Bring the Right Documents

    You’ll need:

    • Your residence card (在留カード / zairyu card)
    • Your passport
    • Your My Number notification card or My Number card (if you have one)
    • A personal seal (inkan) — though many offices now accept signatures for foreigners

    Step 3: Fill Out the Application

    The forms are usually in Japanese, but many larger city offices have multilingual staff or interpretation services. If you’re in a smaller town, this is where having a basic grasp of Japanese or bringing a Japanese-speaking friend really helps. Consider using a language learning app to build up your basics — check out our guide to the best language apps for Japanese.

    Step 4: Receive Your Insurance Card

    You’ll receive your NHI card (健康保険証 / kenko hokensho) either on the spot or by mail within a couple of weeks. In 2026, Japan is also transitioning many insurance functions to the My Number card system, so you may be asked if you want to link your insurance to your My Number card. I recommend doing this — it streamlines hospital visits significantly.

    Step 5: Start Paying Premiums

    Your premium notices will arrive by mail, typically a few weeks after enrollment. You can pay at convenience stores, via bank transfer, or set up automatic payments. More on costs below.

    How Much Does Japan’s National Health Insurance Cost?

    This is the question everyone asks, and unfortunately, there’s no single answer. NHI premiums vary based on several factors:

    • Your municipality: Each city/ward sets its own rates. Premiums in rural areas tend to be lower than in major cities like Tokyo or Osaka.
    • Your income from the previous year: The higher your income, the higher your premium. Japan’s tax year runs January to December, and your income is reported via your annual tax return.
    • Number of household members enrolled: A per-capita charge applies for each person on the plan.
    • Your age: People aged 40-64 pay an additional “long-term care insurance” surcharge.

    Rough Cost Estimates for 2026

    Annual Income (JPY) Estimated Monthly Premium
    First year (no prior Japan income) ¥1,500 – ¥3,000
    ¥2,000,000 ¥8,000 – ¥15,000
    ¥4,000,000 ¥20,000 – ¥35,000
    ¥6,000,000 ¥35,000 – ¥55,000
    ¥8,000,000+ ¥50,000 – ¥65,000 (cap applies)

    First-year bonus: If you’ve just arrived in Japan and had no Japanese income the previous year, your first-year premiums will be very low — often just the flat-rate minimum. Enjoy it while it lasts, because once your income gets reported, year two will be a shock.

    There is an annual cap on NHI premiums (around ¥1,060,000 per household in 2026, though this varies by municipality). Even high earners won’t pay more than this.

    What Does Japan’s National Health Insurance Cover?

    NHI covers an impressive range of medical services at a 70% rate, meaning you pay 30% out of pocket. Here’s what’s included:

    Covered Services

    • Doctor consultations and examinations
    • Prescription medications
    • Surgery and hospitalization
    • Lab tests, X-rays, MRIs, CT scans
    • Mental health consultations and treatment
    • Maternity care (though normal delivery is not covered — it’s not considered “medical treatment”)
    • Dental care (basic treatments)
    • Physical rehabilitation
    • Ambulance services (always free in Japan regardless of insurance)

    Not Covered (or Partially Covered)

    • Cosmetic procedures
    • Normal childbirth (though you receive a lump-sum birth allowance of ¥500,000)
    • Advanced dental work (crowns, orthodontics, implants)
    • Private hospital rooms (the upgrade fee, not the treatment)
    • Some cutting-edge treatments not yet approved for coverage
    • Preventive health checkups (though your municipality likely offers subsidized annual checkups — look into it!)

    The High-Cost Medical Expense Benefit (Kogaku Ryoyo)

    This is one of the most underappreciated features of Japanese health insurance. If your medical expenses for a single month exceed a certain threshold (based on your income bracket), the government reimburses the excess. For most working-age adults, the cap is roughly ¥80,000–¥90,000 per month. This means even if you have major surgery or a long hospitalization, your out-of-pocket costs are capped.

    You can apply for a Limit-Application Certificate (限度額適用認定証) in advance so you never have to pay more than the capped amount at the hospital. Get this before any planned procedure — it saves you from fronting the cash and waiting for reimbursement.

    NHI vs. Private Health Insurance: Do You Need Both?

    This is a common question, and my answer is nuanced. NHI is excellent for day-to-day medical care. But there are situations where supplemental private insurance can fill the gaps.

    Pros of NHI Alone

    • Covers 70% of most medical costs
    • High-cost medical expense cap limits catastrophic bills
    • Accepted at virtually every clinic and hospital in Japan
    • Affordable premiums, especially in your first year
    • No pre-existing condition exclusions

    Cons of NHI Alone

    • No English-speaking doctor guarantee (though many exist in major cities)
    • Doesn’t cover medical evacuation to your home country
    • Limited dental and vision coverage
    • No coverage outside Japan
    • Normal childbirth not covered (though the birth allowance helps)

    When to Consider Private Insurance

    I’d recommend supplemental private insurance if:

    • You want English-language medical support and concierge services
    • You travel internationally frequently and need coverage outside Japan
    • You want comprehensive dental or vision coverage
    • You want income protection during extended illness or hospitalization
    • You want life insurance bundled with health coverage

    Popular options among expats include international plans from companies like Cigna Global, Allianz Care, and local Japanese providers like Aflac Japan or various kyosai (mutual aid) plans. Many expats also keep a travel insurance policy for trips outside Japan.

    Essential Tools and Resources for Managing Healthcare in Japan

    Navigating the healthcare system is much easier with the right tools. Here are my top recommendations:

    A Good Japanese-English Medical Dictionary or Phrasebook

    Even if your doctor speaks some English, you’ll need to fill out intake forms and describe symptoms in Japanese. A medical phrasebook is invaluable. You can find great options here: Japanese-English medical dictionaries on Amazon.

    Translation Apps and Devices

    A pocket translator can be a lifesaver at clinics in smaller towns. I’ve used several, and they’re surprisingly good for medical conversations: pocket translator devices on Amazon.

    A Reliable VPN

    You might wonder what a VPN has to do with health insurance. If you need to access medical records from back home, contact your home country’s insurance portal, or research treatments on region-locked sites, a VPN is essential. Check out our best VPN for Japan guide.

    Medicine Organizer for Prescriptions

    Japanese pharmacies dispense medications in individual packets, and you can end up with a lot of different pills after a single visit. A good pill organizer helps keep things straight: travel pill organizers on Amazon.

    Okusuri Techo (Medicine Notebook)

    Every pharmacy in Japan will give you an okusuri techo (お薬手帳) — a little booklet that tracks all your prescriptions. Keep this with you always and bring it to every pharmacy and doctor visit. You can also get digital versions via smartphone apps. This is one Japanese system that’s genuinely brilliant for tracking your medical history.

    A Practical Guide to Using Your NHI at Clinics and Hospitals

    Here’s what a typical doctor visit looks like in Japan — because the process is different from what most Westerners are used to.

    Step 1: Choose a Clinic

    For non-emergency care, go to a local clinic (クリニック or 医院) rather than a hospital. Hospitals are for referrals and serious cases. Many charge an extra fee (sometimes ¥5,000+) if you show up without a referral letter. Google Maps is surprisingly good for finding nearby clinics — search for the specialty you need (内科 for internal medicine, 皮膚科 for dermatology, 耳鼻科 for ENT, etc.).

    Step 2: Bring Your Insurance Card

    Hand it to the receptionist when you arrive. They’ll copy your information and register you in their system. First visits take longer because of paperwork.

    Step 3: Wait, See the Doctor, Get Treatment

    Waiting times vary but are generally reasonable. The doctor will examine you, and if medications are needed, you’ll receive a prescription. Most clinics handle blood tests and basic imaging on-site.

    Step 4: Pay at the Counter

    After your visit, you pay your 30% co-pay at the reception desk. A standard clinic visit might cost ¥1,000–¥3,000 out of pocket. With blood tests or imaging, maybe ¥3,000–¥8,000. Compared to healthcare costs in the US, this feels almost absurdly affordable.

    Step 5: Pick Up Prescriptions

    Take your prescription to a nearby pharmacy (調剤薬局). There’s almost always one right next to or across from the clinic. Hand them your prescription and your okusuri techo, wait a few minutes, pay, and you’re done. Prescription costs are also covered at 70% by NHI.

    Common Mistakes Foreigners Make with NHI

    After years of helping fellow expats, I see the same mistakes over and over:

    • Not enrolling immediately: If you delay enrollment, you’ll owe back-premiums from the date you became eligible. Japan doesn’t let you skip months.
    • Not reporting income changes: If you leave a job or start freelancing, you need to switch from Shakai Hoken to NHI within 14 days. Miss this window and you’ll have a coverage gap — and back-premiums.
    • Ignoring premium payment notices: Unpaid premiums can result in your insurance card being replaced with a short-term certificate, and eventually, you could lose coverage entirely. This can also affect visa renewals.
    • Not applying for premium reductions: If your income is low, you may qualify for a 70%, 50%, or 30% reduction in premiums. Ask at your ward office.
    • Forgetting to cancel when leaving Japan: When you leave the country permanently, you need to cancel your NHI at the ward office. Otherwise, premiums keep accumulating.

    Frequently Asked Questions

    Can I use Japanese National Health Insurance outside of Japan?

    Technically, yes — but it’s limited and complicated. If you receive emergency medical treatment abroad, you can apply for partial reimbursement after returning to Japan. However, the reimbursement is calculated based on what the treatment would have cost in Japan, not what you actually paid. The paperwork is extensive, and you’ll need itemized receipts translated into Japanese. For regular international travel, I strongly recommend separate travel insurance.

    What happens if I can’t afford my NHI premiums?

    Don’t just stop paying — go to your ward office and explain your situation. Most municipalities offer premium reduction programs for low-income residents. Depending on your household income, you could receive a 20% to 70% discount. Some cities also offer payment plans for those experiencing temporary financial hardship. The worst thing you can do is ignore the bills.

    Is NHI mandatory even if I have private international health insurance?

    Yes. As a registered resident of Japan with a visa of three months or longer, enrollment in either NHI or employer-based insurance is legally required, regardless of any private coverage you hold. Some expats maintain both — NHI for daily use and private insurance for additional benefits or international coverage. You cannot opt out of the public system.

    How does NHI work for dependents and family members?

    Unlike Shakai Hoken, which allows free dependent coverage, NHI charges a per-person premium for each enrolled household member. So if your spouse and children are on your NHI plan, premiums increase. However, children under a certain age have reduced or zero co-pays (many municipalities cover children’s medical costs entirely). Your spouse’s premium is still calculated based on their individual income.

    Will unpaid NHI premiums affect my visa renewal?

    In 2026, immigration authorities in Japan increasingly check health insurance and pension payment records during visa renewals. While unpaid NHI premiums may not automatically result in visa denial, they can count against you — especially for permanent residency applications, where a clean record of tax and social insurance payments is essentially required. Pay your premiums on time, every time.

    Conclusion: NHI Is One of the Best Things About Living in Japan

    Look, I won’t sugarcoat it — dealing with Japanese bureaucracy in a language you’re still learning is exhausting. The premium calculations are opaque, the forms are intimidating, and the system assumes you already know how everything works. But once you’re enrolled and understand the basics, Japan’s National Health Insurance is genuinely one of the most generous and efficient healthcare systems you’ll ever experience.

    You get world-class medical care at a fraction of what it costs in most Western countries. You can see specialists without referrals. You’ll never face bankruptcy from a medical emergency. And that ¥2,000 doctor visit that includes an examination, blood work, and a prescription? It never gets old.

    My biggest piece of advice: enroll the day you register your address, set up automatic premium payments so you never miss one, and get yourself an okusuri techo. Keep your insurance card in your wallet at all times. And don’t be afraid to go to the doctor — in Japan, preventive care and early treatment are the norm, not the luxury.

    Healthcare is just one piece of the puzzle when building your life in Japan. Make sure you’re also set up with the right financial tools — our Wise Japan review covers how to manage money transfers and avoid getting destroyed by exchange rates.

    Welcome to Japan. Your health is in good hands here.
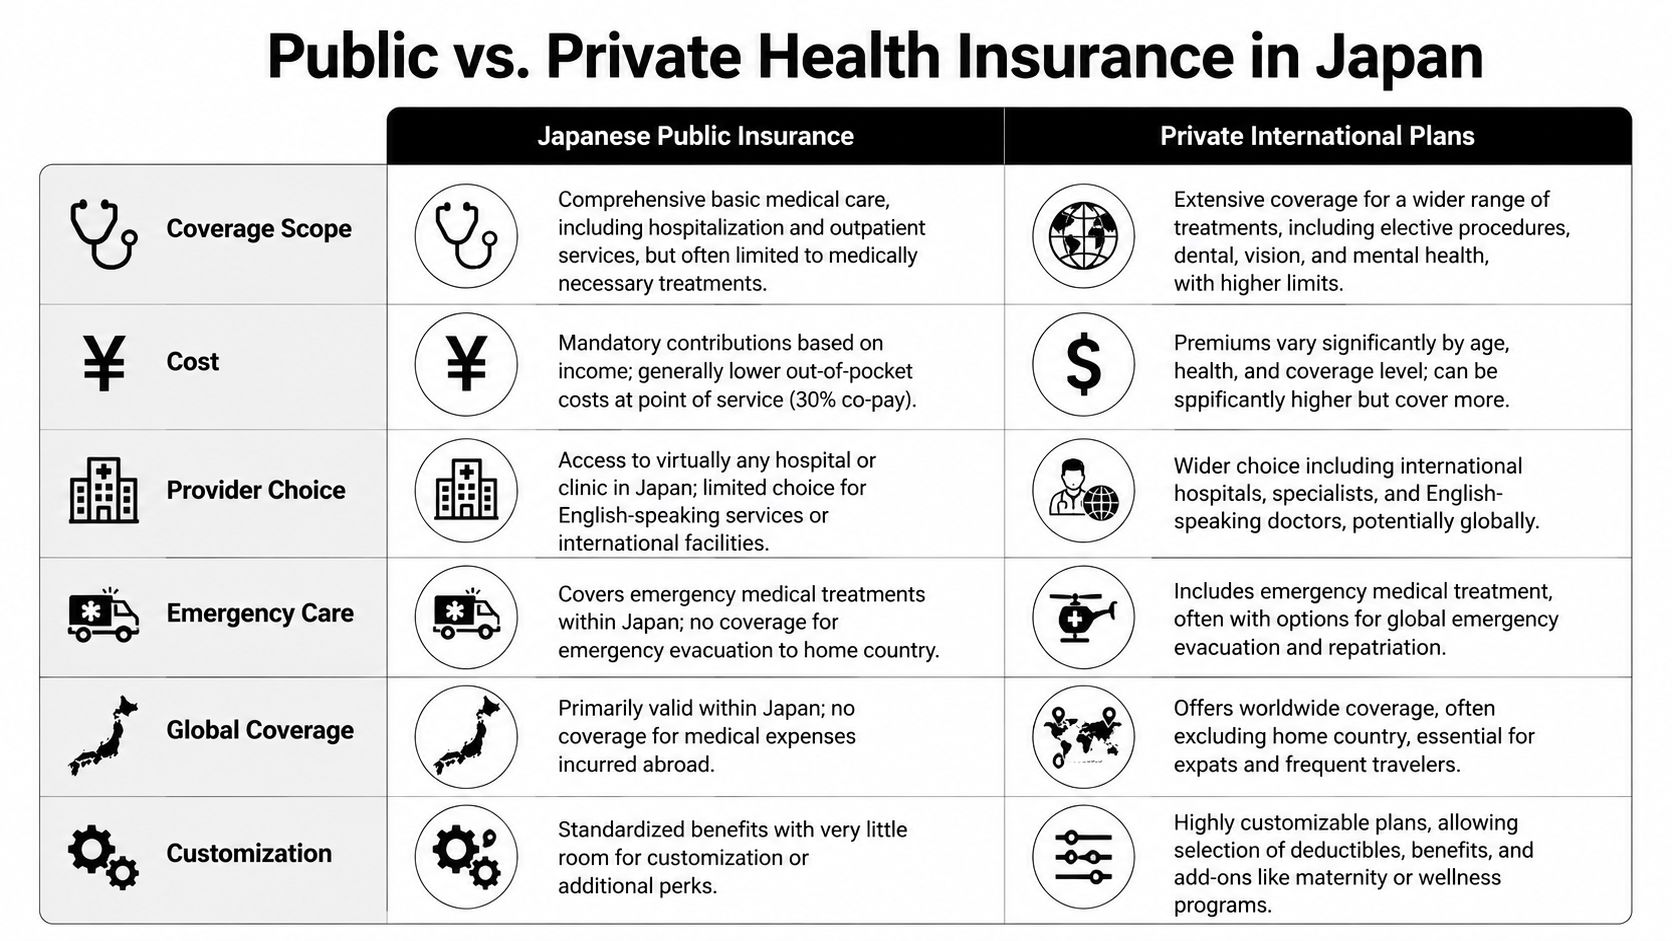
  • Japan Daily Update — 12 August 2026

    “`html

    Your daily Japan news digest for Wednesday, 12 August 2026. Here are today’s top stories relevant to expats and travellers in Japan.

    North Korea fires off second missile in less than a week

    North Korea launched another missile test, marking the second incident in under seven days. While the Defense Ministry confirmed the missile fell outside Japan’s exclusive economic zone, ongoing regional tensions can affect travel advisories and general safety perceptions for those living in or visiting Japan.

    Read full story

    Japan mulls use of domestic AI in SDF command system

    The Japanese government is exploring integration of homegrown artificial intelligence into Self-Defense Force operations as part of broader military modernization efforts. This development reflects Japan’s strategic positioning in the region and could have long-term implications for regional security and stability.

    Read full story

    Gut bacteria may be behind many of Japan’s colorectal cancer cases

    Researchers have identified a toxin called colibactin produced by gut bacteria as a potential factor in Japan’s colorectal cancer cases. This health discovery is relevant for expats planning long-term stays, as understanding local health risks and preventive measures can inform lifestyle and medical decisions.

    Read full story

    Japan end of June government debt hits record ¥1.3 trillion

    Japan’s government debt has reached a historic high as spending continues to outpace tax revenues. Long-term economic trends like rising national debt can influence currency stability, cost of living, and the broader financial environment affecting expats’ purchasing power and savings.

    Read full story

    Check back tomorrow for the latest Japan updates.

    “`


    Compiled daily from Japan Times and GaijinPot. Updated every morning.